Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124

To understand why modern financial markets behave the way they do (why wealth inequality widens during economic crises, why national debt climbs continuously, and why asset prices decouple from real wages), investors must look beyond conventional economic textbooks. Most public commentary focuses on short-term political narratives, quarterly central bank announcements, or surface-level media coverage. However, as former investment banker Simon Dixon outlines in his forensic breakdown of global capital structures, understanding the true nature of power and economic direction requires ignoring political speeches and tracking the exact movement of monetary flows.
[Also Read: 1971 Was Not a Coincidence – Who Got Rich Afterwards]
Every modern economy operates under a capital structure that dictates who holds power, who assumes risk, and who extracts value. By analyzing capital structures, funding mechanisms, and the institutional incentives behind major financial flows, a clearer historical picture emerges: our financial system was not designed to store value or promote equitable market competition, but rather to institutionalize debt and concentrate capital ownership.
This article is Part 1 of a three-part series for Market Mind Investor (MMI), breaking down the hidden history of money and systemic finance. In this opening installment, we examine the origins of paper currency, the birth of fractional reserve banking, the structural flaw of debt-based money, and how the 17th-century Dutch Republic invented the modern financial triad that continues to govern global markets today.
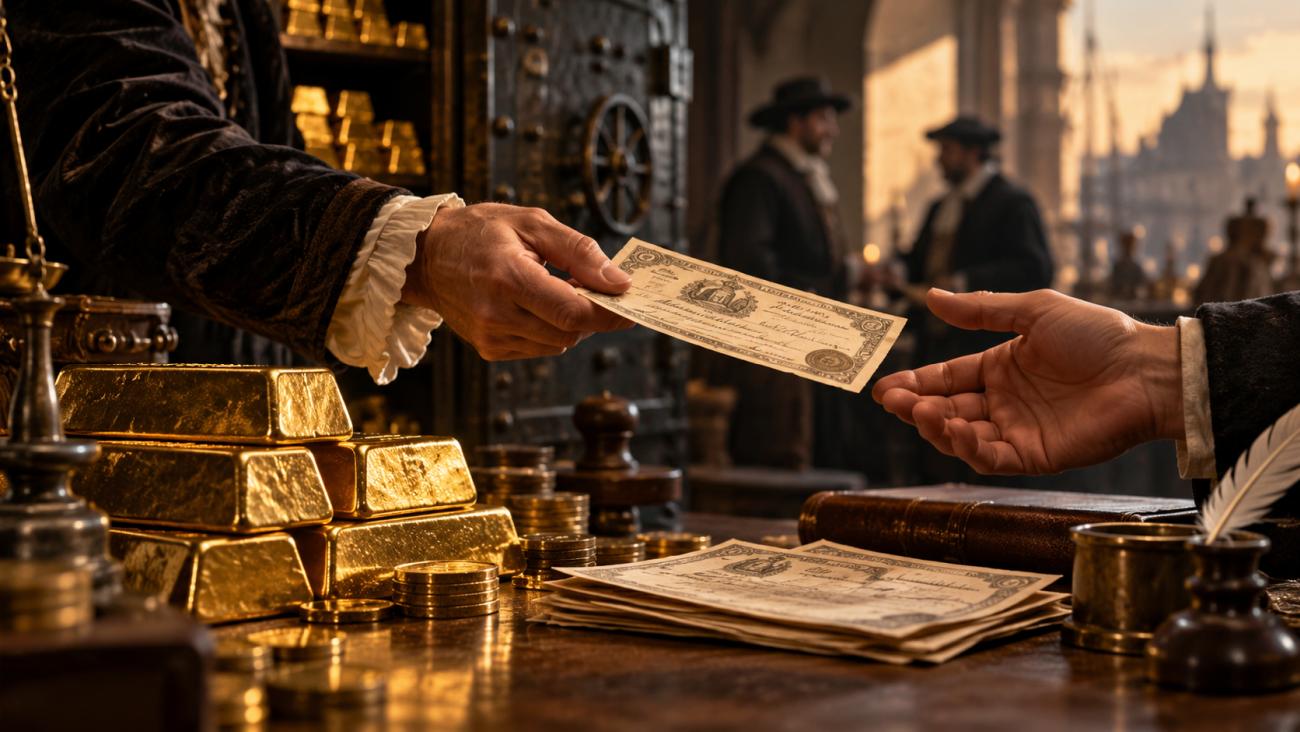
The modern banking system traces its conceptual roots to medieval and early modern goldsmiths. Long before central banks or digital ledgers existed, physical gold was universally recognized as the ultimate form of money and the means of settling trade. However, holding and transporting physical gold carried immense security risks and logistical burdens. Merchants and individuals sought a safe haven for their bullion, turning to local goldsmiths who possessed reinforced vaults and specialized security.
When a customer deposited gold bullion with a goldsmith, the goldsmith issued a paper receipt acknowledging the deposit. These receipts stated that the bearer was entitled to redeem a specific quantity of physical gold upon demand. Initially, depositors used these paper receipts purely as storage receipts, taking them back to the vault whenever they needed physical metal to complete a transaction.
Over time, trade participants realized that carrying paper receipts was vastly more efficient than hauling heavy chests of gold across cities. As public trust in the goldsmiths grew, merchants began accepting the paper receipts directly as payment for goods and services, rather than demanding the physical gold itself. In 17th-century London, these receipts were passed from hand to hand as an early form of paper money, the ancestors of today’s banknotes. The goldsmith’s vault remained largely untouched while the paper notes circulated continuously through the economy.
This behavioral shift created an unprecedented financial epiphany for goldsmiths. By observing vault activity over extended periods, goldsmiths realized that only a small fraction of depositors ever returned at any given time to convert their paper receipts back into physical metal. The vast majority of the gold sat idle in the vaults indefinitely, serving merely as psychological backing for the paper notes circulating outside.
Once goldsmiths recognized that the physical gold in their vaults remained largely unclaimed, they identified a lucrative, albeit deceptive, business opportunity. Individuals continuously approached goldsmiths seeking loans to finance trade, property, or commercial ventures. Rather than lending out their own capital or asking existing depositors for permission to re-lend their bullion, goldsmiths began printing and issuing brand-new paper receipts to borrowers out of thin air.
These newly printed receipts were identical in appearance to the legitimate receipts backed by actual gold deposits. The goldsmith issued these unbacked notes to borrowers, charging interest on the loan. The borrower would then spend the notes into the economy, where they circulated alongside genuine deposit receipts. Through this mechanism, goldsmith bankers collectively created credit, and with it new purchasing power, from nothing, backed by only a fraction of the physical reserves held in their vaults.
In essence, the original goldsmiths committed systemic fraud by issuing multiple paper claims against the same bar of gold. This practice worked seamlessly as long as public confidence remained intact. However, if rumors spread that a goldsmith had issued far more paper notes than he held in gold reserves, panic ensued. Depositors and noteholders would rush to the vault simultaneously to convert their paper receipts into physical metal before the gold ran out.
These panics, the earliest iterations of a bank run, inevitably exposed the fraud. Because the goldsmith had issued receipts far exceeding his actual gold reserves, the vault would be drained almost immediately. Latecomers were left with worthless paper, the bank defaulted, and local credit collapsed.
Rather than outlawing this fractional creation of paper claims, sovereign governments and monarchs recognized its strategic advantage. State treasuries were frequently in debt due to foreign wars and administrative expenses. Politicians and monarchs realized that by partnering with the banking interest, the government could secure loans financed by paper creation. In exchange, the state legalized fractional reserve banking, providing legal protections to bankers, establishing official reserve ratios (such as requiring 10% gold backing while permitting 90% unbacked credit expansion), and positioning the government as the ultimate guarantor of the monetary framework.
The transition from commodity-backed currency to fractional reserve banking established a fundamental mathematical dynamic that governs modern finance: money is issued into existence as commercial debt. Today, the overwhelming majority of money in modern economies exists as bank credit created through commercial lending. In the UK, the Bank of England has estimated that bank deposits make up roughly 97% of broad money in circulation, with physical currency accounting for only a tiny fraction of the total.
When a commercial bank issues a loan, whether a corporate loan, a mortgage, or a government bond purchase, it does not transfer money from another customer’s savings account. Instead, the bank writes a new asset and liability onto its balance sheet, creating brand-new money in the borrower’s account. However, this process contains a built-in structural defect regarding interest.
When a bank creates and lends $100 into the economy, it creates only the principal amount. Yet the loan agreement requires the borrower to repay the principal plus interest, for instance $110 over the duration of the term. While the bank created the initial $100 principal, neither the bank nor the monetary system created the additional $10 needed to pay the interest.
Because total aggregate debt always exceeds the total amount of money in existence, the financial system faces a permanent monetary deficit. Borrowers across the economy must compete against one another for a pool of money that is inherently insufficient to service both total principal and aggregate interest obligations.
To prevent widespread default, economic collapse, and systemic debt deflation, the total money supply must continuously expand. The system requires continuous new borrowing, by individuals taking on larger mortgages, corporations issuing debt, or governments running fiscal deficits, simply to generate enough money to pay the interest on pre-existing debt. This mathematical reality transforms the monetary system into a structural Ponzi architecture, driving perpetual debt expansion, currency debasement, and relentless upward pressure on real asset prices.
While fractional reserve credit evolved organically through European merchant networks, the formal architecture of institutional finance was invented in the early 17th century by the Dutch Republic. Around 1600, the Dutch introduced three interconnected financial mechanisms that transformed global commerce, war finance, and capital accumulation.
The Central Bank. The creation of publicly chartered banking institutions, beginning with the Bank of Amsterdam (Wisselbank) in 1609, provided a centralized clearinghouse for currency, government debt, and commercial credit settlement, acting as the ultimate guarantor of the banking system.
The Public Stock Market. Exemplified by the founding of the Dutch East India Company (Vereenigde Oostindische Compagnie, or VOC) in 1602, the Dutch established the world’s first public equity market. This allowed private investors to pool capital, trade shares, and securitize commercial enterprises, privatizing the massive profits derived from global trade and colonial ventures.
The Tradable Bond Market. The Dutch financial system turned government debt into tradable financial securities. State obligations were converted into liquid instruments that could be bought, sold, and leveraged by private financial institutions.
This three-pillar model established a sophisticated mechanism for wealth concentration. By combining a central bank guarantor, an equity market for corporate gains, and a bond market for state debt, the system created a structural division within the economy. Profit and capital growth from global commercial expansion were privatized into equity markets for asset owners, while the risks, systemic losses, and debt obligations were socialized onto the public state balance sheet through government bonds and taxation.
Armed with this superior financial engineering, naval dominance, and corporate structure, the Dutch East India Company became the dominant economic force in the world, extracting raw materials, controlling trade routes, and demonstrating that financialization was far more lucrative than traditional agrarian production.
The immense power generated by the Dutch financial architecture did not remain confined to Amsterdam. As the Dutch Republic faced geopolitical constraints and rising military conflicts, its financial technology was adopted and expanded by Britain. Following the Glorious Revolution of 1688, which placed the Dutch stadholder William of Orange on the English throne, Dutch financial techniques were formally imported into London.
In 1694, the English government established the Bank of England to fund its war against France. The Bank of England was structured as a private institution that extended loans to the Crown in exchange for the privilege of issuing paper bank notes and managing state debt. Alongside it, the East India Company, chartered in 1600 and later known as the British East India Company, replicated the Dutch East India Company model, privatizing corporate profits while utilizing state military power to secure commercial trade routes.
Throughout the 18th and 19th centuries, merchant banking interests operated within this imperial capital structure, with the Rothschild family rising to become the most prominent of them by the early 1800s. These financial institutions recognized that by underwriting government bonds and funding sovereign states, they could subordinate governments to their financial balance sheets.
During major European wars, merchant banks frequently lent to governments on more than one side of a conflict. Financing the war effort generated massive bond yields; financing the subsequent post-war reconstruction generated further corporate contracts; and the debt accumulated by sovereign governments guaranteed long-term interest payments extracted from taxpayers. If a government defaulted or attempted to resist its financial obligations, international bondholders could restrict credit, collapse the national currency, or support rival political factions.
Through this model, the British Empire transferred unprecedented wealth from global colonies and domestic working populations into the balance sheets of institutional financiers and asset owners. Government debt expanded continuously, corporate equities appreciated, and the financial sector established supreme authority over state policy.
Understanding the origins of paper currency, fractional reserve creation, and the Dutch-British financial triad provides investors with a crucial diagnostic framework for analyzing contemporary markets. The financial mechanisms operating today are not modern inventions; they are direct continuations of a 400-year-old financial architecture designed to manage debt expansion and capital concentration.
When modern central banks lower interest rates, initiate quantitative easing, or monetize government debt, they are exercising the same guarantor function established by the Dutch and British central banks centuries ago. When debt expands faster than GDP, it is not an administrative accident, but the mathematical outcome of a debt-based monetary system where interest obligations permanently exceed the supply of money.
In Part 2 of this Market Mind Investor series, we will explore how this imperial financial framework crossed the Atlantic during the 20th century, tracing the establishment of the Federal Reserve in 1913, the concentration of global gold in Fort Knox, the creation of the Bretton Woods system in 1944, and the ultimate shift to the Petro-Dollar framework in 1971.