Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124


Two central banks raised interest rates this week, the 10-year US Treasury yield pushed back above 5%, and Washington’s flagship crypto bill died in the Senate. By any traditional playbook, this was a week for risk assets to bleed. Instead,…
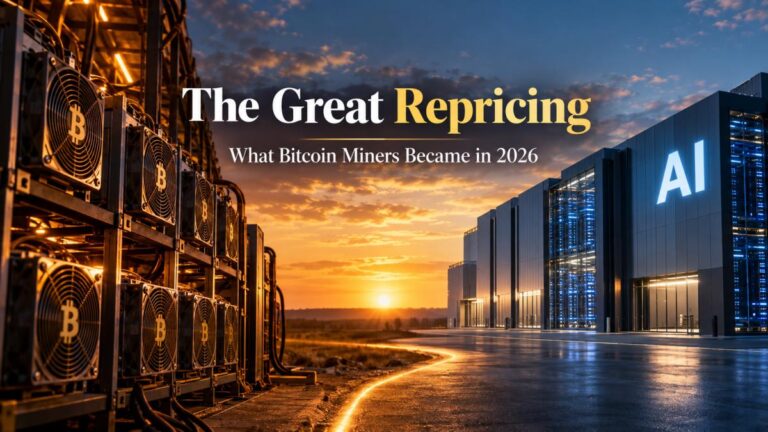
On 10 August, Riot Platforms announced a twenty year data centre lease at its Rockdale, Texas campus and declined to name the tenant, describing it only as one of the world's leading frontier AI labs. The shares fell more than five percent after hours. Then CNBC reported the tenant was Anthropic, and the stock climbed as much as twenty five percent...
Every condition the safe-haven thesis asked for has now arrived. Bitcoin is still trading at half its peak. Start with the tape, because the tape is the argument. Bitcoin sits near $63,000. Its record high was $126,080, which means the asset is down roughly fifty percent from the top and has been grinding lower beneath every major daily moving average — not a crash, a slow bleed. Over the same stretch, the S&P 500 printed a record high and closed out its third consecutive weekly gain. Gold is hovering around $4,400 an ounce after a year that most institutions still describe as structurally supported.

On 4 August, Vladimir Putin signed the Law on Digital Currencies and Digital Rights. The headlines wrote themselves: Russia legalises crypto. It is a tidy line, and it is wrong in a way that matters, because it collapses two separate pieces of legislation into one story and then draws the opposite conclusion from the one the architecture supports.
In the space of forty-eight hours this week, two events took place on opposite sides of the Atlantic that almost nobody in mainstream financial media has connected. On June 30, a consortium of more than 140 of the largest payment, banking, and technology companies on the planet announced a new digital dollar.
Bitcoin slid under $60,000 this week, and the usual chorus arrived right on schedule. Half the market calls it a generational entry point. The other half calls it the first crack in a structure that was never sound to begin with. Both camps are talking their book, and neither is looking very hard at the numbers. So let us look at the numbers, because the data tells a less dramatic and far more useful story than either side wants to admit.
Every cycle hands contrarians the same temptation: wait for the miners to break, then back up the truck. The logic is seductive because it has worked before. When the people who literally manufacture the asset can no longer afford to keep the machines running, the marginal seller is exhausted, the float tightens, and price tends to find a floor. The problem with treating that as a mechanical buy signal in 2026 is that the conditions which made it reliable have quietly eroded, and the data this month says the squeeze is genuine but unfinished.
For most of its existence, the quantum threat to Bitcoin lived in the same mental drawer as alien contact and asteroid strikes: theoretically real, practically ignorable, and useful mostly for headlines. That drawer is now jammed open. Across the first half of 2026 a sequence of research papers, testnet deployments, and institutional warnings has shifted the conversation from whether Bitcoin needs to worry about quantum computing to whether it has left itself enough time to do anything about it. The honest answer is uncomfortable: the network can almost certainly be saved, but a meaningful slice of its supply may already be beyond saving.
On May 29, 2026, at 4:00 p.m. Central Time, a technical pattern that had defined Bitcoin trading since 2017 ceased to exist. The CME gap, one of the most reliably watched signals in all of crypto technical analysis, was not killed by a market crash or a regulatory ruling. It was killed by the logical conclusion of institutional adoption: the world's largest regulated derivatives exchange finally conceding that an asset trading 24 hours a day, seven days a week cannot be adequately served by a venue that closes for the weekend.
The "digital gold" narrative has been the load-bearing wall of Bitcoin's institutional investment thesis for the better part of a decade. The idea was elegant and easy to communicate: fixed supply, no central bank, immune to debasement, a hedge for the monetary chaos that fiat systems periodically produce. Sovereign wealth managers understood it. Family offices modelled it. Pension consultants used it to justify allocation. In 2026, the empirical data is dismantling it in real time, and the investors who are clearest about what is actually happening will be best positioned for what comes next.