Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124

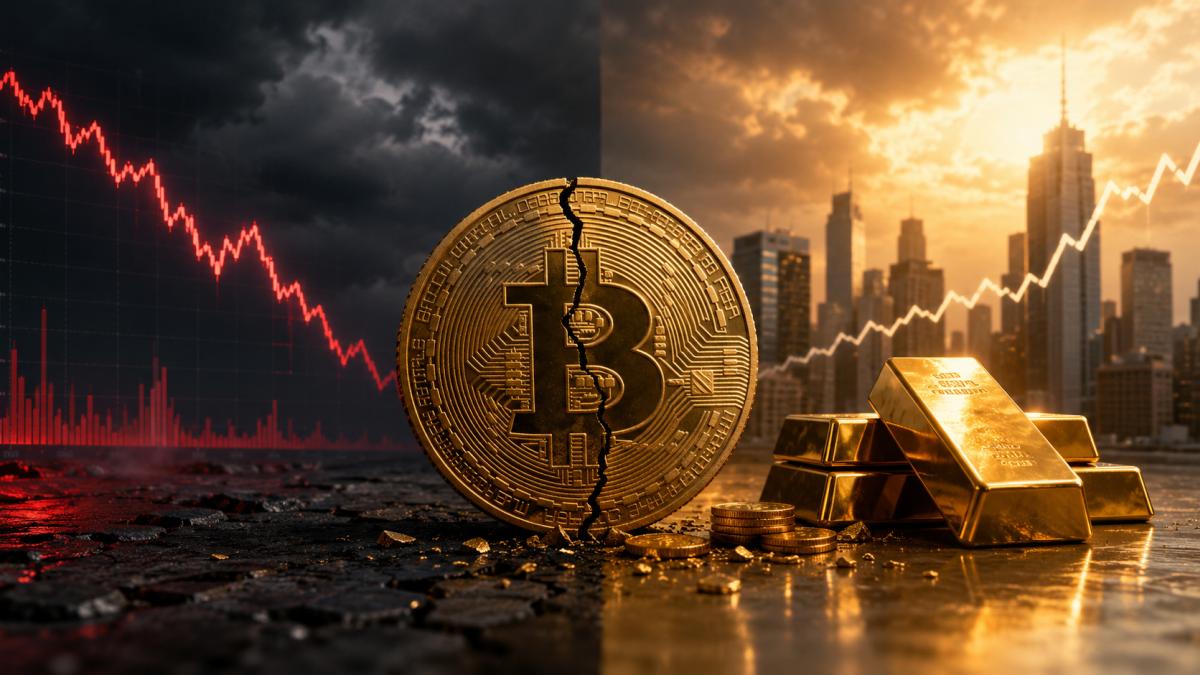
Every condition the safe-haven thesis asked for has now arrived. Bitcoin is still trading at half its peak. Start with the tape, because the tape is the argument. Bitcoin sits near $63,000. Its record high was $126,080, which means the asset is down roughly fifty percent from the top and has been grinding lower beneath every major daily moving average — not a crash, a slow bleed. Over the same stretch, the S&P 500 printed a record high and closed out its third consecutive weekly gain. Gold is hovering around $4,400 an ounce after a year that most institutions still describe as structurally supported.
Every condition the safe-haven thesis asked for has now arrived. Bitcoin is still trading at half its peak.
Start with the tape, because the tape is the argument. Bitcoin sits near $63,000. Its record high was $126,080, which means the asset is down roughly fifty percent from the top and has been grinding lower beneath every major daily moving average — not a crash, a slow bleed. Over the same stretch, the S&P 500 printed a record high and closed out its third consecutive weekly gain. Gold is hovering around $4,400 an ounce after a year that most institutions still describe as structurally supported.
So the hedge is halved while the thing it was supposed to hedge against is at an all-time high.
This is the part that should bother anyone holding the position. It is easy to explain a hedge that fails during a panic — panics are liquidity events, everything correlates to one, the hedge gets sold alongside everything else and recovers afterward. That story has been told about Bitcoin repeatedly and it has always contained some truth. But there is no version of the digital-gold thesis that survives an asset losing half its value during an equity melt-up. That is not a liquidity event. That is a repricing.
It was always conditional, and the conditions were specific. Bitcoin would appreciate because fiat currencies would be debased, because the dollar’s reserve status would erode, and because institutional capital would eventually treat scarcity as a portfolio input rather than a curiosity. Three legs. Every one of them has been tested in the last eighteen months, and this publication has covered each as it happened.
Debasement arrived. Central banks are sitting on enormous mark-to-market losses on bond books they accumulated during the easing years, and those losses are being socialised through the fiscal channel rather than recognised. That is monetary dysfunction of exactly the kind the thesis anticipated.
De-dollarization arrived, and then some. Deutsche Bank’s research arm documents the dollar’s share of global central bank reserves falling from a peak above sixty percent to around forty percent today, while gold’s share tripled from its lows to nearly thirty percent. The geopolitical logic behind it is not subtle: the freezing of roughly $300 billion in Russian reserves in 2022 demonstrated that dollar assets can be weaponised, and the global south drew the obvious conclusion. Russia has since gone further and formally bifurcated its own monetary system. If you had described that scenario to a Bitcoin maximalist in 2021 and asked what price it implied, you would not have been told sixty-three thousand.
Institutional adoption arrived. We covered MicroStrategy’s eleven-week accumulation streak at the time, and the framing then was that persistent corporate buying signalled durable institutional confidence in Bitcoin as a store of value. The buying was real. The confidence was real. The position is enormous. And it has not held the price up.
Three for three. The world delivered precisely the macro environment the thesis specified, and the asset went down by half.
There was a clean natural experiment earlier this year and it has been quietly memory-holed by people who did not like the result. When the Iran conflict opened on 27 February, both assets were tested against the same shock at the same moment. In the first forty-eight hours, gold rose 5.2 percent and Bitcoin fell 12 percent.
That is not ambiguous. Presented with a textbook geopolitical shock, capital went to the metal. And it kept going — central banks have bought more than a thousand tonnes of gold in each of the last three years, which is the single most revealing flow in global macro right now. The institutions with the longest horizons, the least performance pressure and the most direct exposure to currency risk have been making their choice with real money for three consecutive years, and they are not choosing Bitcoin.
The uncomfortable summary is that the conditions for Bitcoin to fulfil its promise all materialised — currency debasement, de-dollarization fears, geopolitical conflict — and the flows went overwhelmingly into precious metals instead.
Here is the mechanism, and it is less philosophical than the debate usually allows.
Speculative capital is not loyal to a narrative. It is loyal to the best available risk-adjusted return over its holding period, and for most of this cycle that has been semiconductors. Wolfe Research’s Rob Ginsberg put the trade-off about as bluntly as a sell-side analyst can: “Who in their right mind would rather buy crypto right now” when a chip stock could multiply in weeks.
That is the whole story of the divergence in one sentence. Bitcoin has not been competing with the dollar. It has been competing with Nvidia. And on a twelve-month view it lost that competition badly enough that the marginal speculative dollar simply stopped showing up. The asset was never functioning as a hedge in the first place; it was functioning as the highest-beta expression of risk appetite available to retail, and when a higher-beta expression appeared with a better story attached, the flow rotated.
This also explains something that otherwise looks contradictory. Bitcoin ETFs took in roughly $850 million even as price ground lower. Allocators are still buying. The bid exists. It is simply smaller than the supply coming the other way — and a persistent institutional bid that cannot arrest a fifty percent drawdown tells you the marginal seller is larger and more motivated than the marginal buyer. Inflows are not a bullish signal in isolation. They are only bullish relative to what is being sold into them.
The reflexivity risk is worse than the flows suggest. Reporting indicates that when Strategy disclosed a sale of thirty-two coins — 0.0038 percent of a position of 843,700 BTC — the market treated a rounding error as a regime change and sold off hard. An asset where an immaterial transaction moves the price that much is an asset priced on narrative rather than flow. That is a structural fragility, not a sentiment blip, and it is worth verifying independently before sizing anything around it.
There is one, and it deserves stating properly rather than being strawmanned.
The sequencing argument holds that gold and Bitcoin are not competitors but consecutive stages of the same trade. Gold rallies first, when real yields fall and panic is acute; Bitcoin follows later, as liquidity improves and risk appetite returns — a staggered reaction rather than a contest. On that reading, gold is the first-line refuge and Bitcoin is the follow-up hedge, and what we are watching is not failure but lag.
It is a genuinely good argument and it has historical support. It also has a problem: the follow-up leg was supposed to have arrived by now. Risk appetite did return — that is what a record-high S&P and a semiconductor melt-up mean. Liquidity did improve. The conditions for stage two were met and stage two did not happen. At some point a lag long enough to span an entire risk-on cycle stops being a lag.
The steelman that survives is narrower and more interesting: Bitcoin’s infrastructure has matured enormously — regulated ETF access, deep 24/7 liquidity, institutional custody — and infrastructure maturity historically precedes price recognition by years, not months. That may well be right. But notice what it concedes. It is a five-year adoption argument, not a hedge argument. It tells you to size the position as a venture-style bet on eventual monetisation, not as portfolio insurance against the exact macro environment we are currently living through.
Reprice the job, not just the asset.
If Bitcoin is in your portfolio doing the work that gold is supposed to do, the last eighteen months have given you an unusually clean answer, and it is not the one the position was built on. The hedge role is empirically occupied. Central banks, the least sentimental buyers in the world, have voted with a thousand tonnes a year, three years running.
If Bitcoin is in your portfolio as a high-beta bet on liquidity and adoption, that is defensible — but size it as what it is. That means accepting drawdowns correlated with risk assets rather than inverse to them, and it means never again counting it as the defensive sleeve. The most expensive mistake available here is holding a risk asset while believing you hold insurance, because you will discover the difference at precisely the moment you need the insurance to work.
And watch the sequencing thesis honestly. It is falsifiable, which is more than most crypto arguments manage. If the next genuine risk-off shock produces the same split — metal up, Bitcoin down — that is three data points across three different shocks, and three is a pattern. The thesis will have had every condition it asked for and failed each time.
The market has been telling you something for eighteen months in the plainest language available. Everything the story predicted came true. The price went the other way. When the world cooperates completely and the asset still doesn’t move, the problem was never the world.