Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124

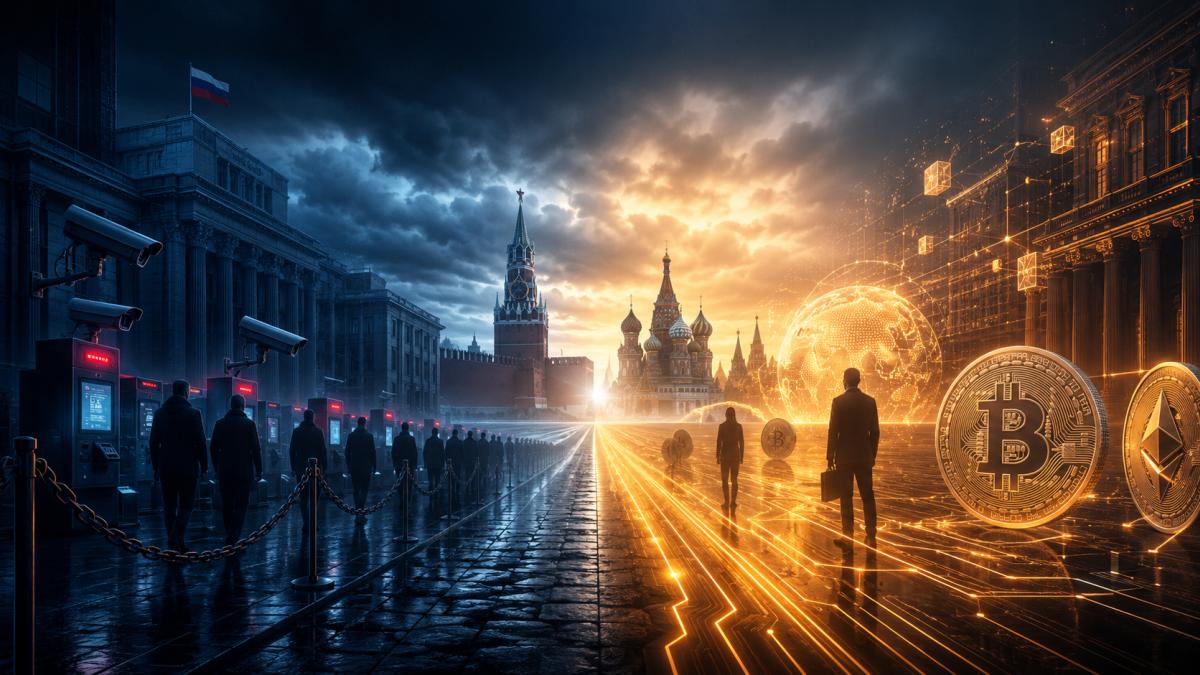
On 4 August, Vladimir Putin signed the Law on Digital Currencies and Digital Rights. The headlines wrote themselves: Russia legalises crypto. It is a tidy line, and it is wrong in a way that matters, because it collapses two separate pieces of legislation into one story and then draws the opposite conclusion from the one the architecture supports.
On 4 August, Vladimir Putin signed the Law on Digital Currencies and Digital Rights. The headlines wrote themselves: Russia legalises crypto. It is a tidy line, and it is wrong in a way that matters, because it collapses two separate pieces of legislation into one story and then draws the opposite conclusion from the one the architecture supports.
Two things commence on 1 September 2026. The first is the new crypto framework, which passed the State Duma on 22 July and creates Russia’s first licensed market for digital asset trading. The second is the large-scale rollout of the digital ruble, the central bank digital currency that has been law since 2023 and has spent three years in pilot. Its operating statute, Federal Law No. 340-FZ, made the Bank of Russia the platform operator and wrote digital rubles into insolvency, currency control and enforcement law. The pilot control period expires on 31 August. The mandate begins the next morning.
Same date. Opposite instruments. That is not a scheduling coincidence, and reading it as one is how you end up describing a tightening as a liberalisation.
Start with what it does not do. The ban on using cryptocurrency to pay for goods and services inside Russia stays exactly where it was. You will not be settling a restaurant bill in Moscow with Bitcoin in September, or in 2027, or under this statute at all.
What changes is that ownership and trading move from a tolerated grey zone into a permissioned one. Under the framework reported in detail by The Moscow Times, exchanges, brokers, custodians and other service providers must hold Bank of Russia licences by 1 July 2027. All transactions, custody and record keeping must occur inside that regulated perimeter. Banks are required to reject transfers to unauthorised providers, which turns every commercial bank into an enforcement node rather than a bystander.
Retail access is rationed rather than opened. Investors must pass a knowledge test. Those not classified as qualified, roughly 98 percent of Russian investors by the central bank’s own count, may buy no more than 300,000 rubles (about $3,840) of cryptocurrency per year through any single intermediary. The admissible asset list is defined by thresholds rather than discretion: average market capitalisation above 5 trillion rubles and average daily volume above 1 trillion rubles over the preceding two years. First Deputy Governor Vladimir Chistyukhin has indicated Bitcoin, Ether and USDT clear those bars. Everything else waits on a board decision.
Mining is now formal economic activity with registration requirements for companies and household consumption caps for individuals, though the state simultaneously imposed a regional prohibition covering Moscow and parts of Kursk running from 15 August 2026 to the end of 2032 on grid load grounds. Recognition and restriction arriving in the same package is the pattern, not the exception.
Buried in the detail is the provision that explains the entire design. Transfers into and out of self-custodied wallets, where the holder controls their own private keys, are tightly gated. Only companies engaged in foreign trade may move cryptocurrency directly to a self-custodied wallet. Individual investors must first route assets to a foreign custodial wallet before any transfer to cold storage.
Read that as a monetary instruction rather than a compliance detail. The state has granted exit velocity to exporters and importers, and denied it to citizens. Self-custody is the property that makes crypto usable for sanctions-resistant settlement, and it has been allocated precisely to the population that needs it for that purpose. Everyone else gets an asset class with a spending ban, a purchase cap and a custodian.
That is the two-lane system in a single clause. Cross-border settlement gets the escape hatch. Domestic money gets the ledger.
The digital ruble side is the mirror image, and it is where the compulsion sits. The Bank of Russia’s own statement on the rollout sets the schedule plainly. Major banks must offer digital ruble accounts, transfers and payments from 1 September 2026. Retailers banking with those institutions and turning over more than 120 million rubles in the prior year must accept digital ruble payments from the same date. Banks with a universal licence and merchants above 30 million rubles follow on 1 September 2027. Everyone else arrives by September 2028, with outlets under 5 million rubles exempt.
The same law sets timelines for a universal QR code built on the National Payment Card System, as covered when the bill passed. All banks must support the universal code by 1 September 2026. It will initially route the Faster Payments System, bank platforms and buy-now-pay-later, with digital rubles added later. The code is generated fee-free. Individual transactions in digital rubles carry no charge.
The official framing is that participation is voluntary: nobody is forced to open a wallet, and consumers choose their payment method. That framing is accurate at the wallet layer and irrelevant at every other layer. The obligation falls on the banks people already use and the merchants they already shop at. A currency that is optional for the citizen and compulsory for the entire commercial surface around the citizen is not really optional in the way the word implies. Elvira Nabiullina told the St. Petersburg congress in July that everything is ready for wide use, and the twelve systemically important banks are reported as connected, with one or two possibly taking deferrals into late 2026.
Demand is the weak point, and the state knows it. Banks are being paid a small per-transaction commission on payroll credits to carry the thing. Survey work has consistently found that most Russians cannot articulate why a third form of money is needed alongside cash and deposits, and only around one in ten economically active respondents would accept a full salary in digital rubles. The Human Rights Foundation’s tracker documents the pilot’s slow expansion and the central bank’s confirmation that transactions will be monitored for anti-money laundering compliance by both commercial banks and the regulator itself. Nabiullina has also floated smart contract functionality for business payments and the possibility of wallets sitting on bank balance sheets rather than the central bank’s.
Put the two lanes side by side and the design intent is legible. Russia is separating the settlement layer from the payments layer and applying opposite transparency regimes to each.
Domestically, money becomes more observable. A CBDC with mandatory merchant acceptance, unified QR acceptance, AML monitoring at two levels and programmable conditionality under active development is a payments system with a full audit trail by construction. Externally, settlement becomes less observable, at least to Western authorities. Exporters and importers get unrestricted use of crypto for cross-border payments, direct access to self-custody, and a licensed intermediary layer to move value out.
The stated volumes give a sense of scale. The Finance Ministry has put domestic crypto turnover near 50 billion rubles a day. Russia has reportedly conducted around $11 billion in international trade using cryptocurrency over roughly the past year. Against that, the central bank estimated Russians held about 720 billion rubles (roughly $9.2 billion) on centralised exchanges after the market drawdown, with Bitcoin accounting for around half. This is a real but not systemically enormous pool, which is itself informative: the point is the channel, not the current throughput.
Brussels moved first, and pre-emptively. The EU adopted its 20th sanctions package on 23 April 2026, with crypto measures applying from 24 May. The structural change matters more than the designations. As Elliptic’s analysis sets out, earlier rounds named individual platforms; this one bans an entire category, so any newly established Russian exchange sits inside the prohibition from birth. That closes the successor-platform loop that made previous designations a game of whack-a-mole.
The asset list expanded too. RUBx and the digital ruble joined the ruble-backed A7A5 stablecoin on the prohibited list, and EU persons are barred from supporting the CBDC’s development. TRM Labs noted the timing explicitly: the digital ruble ban was written before the CBDC existed at scale, closing the channel in advance rather than in response. Chainalysis framed the package as a doctrinal shift, the first time crypto assets became a primary rather than incidental target, with the same treatment extended to Belarus.
Here is the resulting bind, and it is sharper than it first appears. Sanctions risk attaches to the regulated venue, not the grey one. Russian market participants have already warned that addresses associated with licensed domestic platforms may attract more scrutiny abroad, not less, which makes the legal channel unattractive to anyone who actually wants their coins to travel. The plausible outcome is that formalisation drives sophisticated volume offshore and captures the conservative, tax-compliant, long-horizon holder who was never the sanctions story to begin with.
A settlement rail is only as good as its willing counterparties. Legalising a Bitcoin leg in Moscow does nothing if the Chinese or Indian or Emirati bank on the other side declines it, and every incremental Western measure raises the cost of being that bank.
Strip away the sanctions context and the interesting part is the divergence in how large economies are resolving the same question. Russia is building a retail CBDC with statutory acceptance mandates and simultaneously fencing private digital assets into a licensed corridor. The United States has moved the other way, with provisions attached to a pending housing bill that would bar the Federal Reserve from issuing a digital dollar until 2030, while private stablecoins expand into the settlement role a CBDC would otherwise occupy. Europe is somewhere in between, advancing a digital euro on a slower timetable while MiCA does the regulatory work on the private side.
Three jurisdictions, three answers to whether the state or the market should own the digital settlement layer. Russia’s answer is the most explicit, and its position as the most sanctioned major economy on earth is what makes it legible: when your access to the incumbent system is contested, you are forced to state your monetary preferences out loud rather than leaving them implied in a decade of consultation papers.
Three markers over the next twelve months. Whether MOEX, Sber, VTB and T-Bank actually launch functioning digital depositories, or whether the closed-loop design keeps assets from moving anywhere useful. Whether cross-border crypto settlement volume grows after 1 September or stalls on counterparty refusal. And whether any other state copies the template, because that is the part that generalises: a fully surveilled domestic CBDC paired with a permissioned crypto corridor for external trade is a governance model, not a Russian peculiarity.
The strongest argument against reading this as a monetary innovation is that it is simply capital control with better branding. A 300,000 ruble annual cap, a knowledge test, a licensing cliff, and a self-custody gate that opens only for approved corporates describe a state managing outflows, not a state building the future of money. On that reading the CBDC is a domestic retail rail nobody asked for, the crypto framework is a tax-base formalisation exercise, and the pre-emptive EU ban demonstrates how quickly the perimeter closes around anything that works.
Both readings can be right at once. What is not defensible is the headline. Russia did not liberalise anything on 4 August. It drew a line down the middle of its monetary system and made the two halves obey opposite rules, and it starts enforcing both on the same Tuesday morning.