Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124

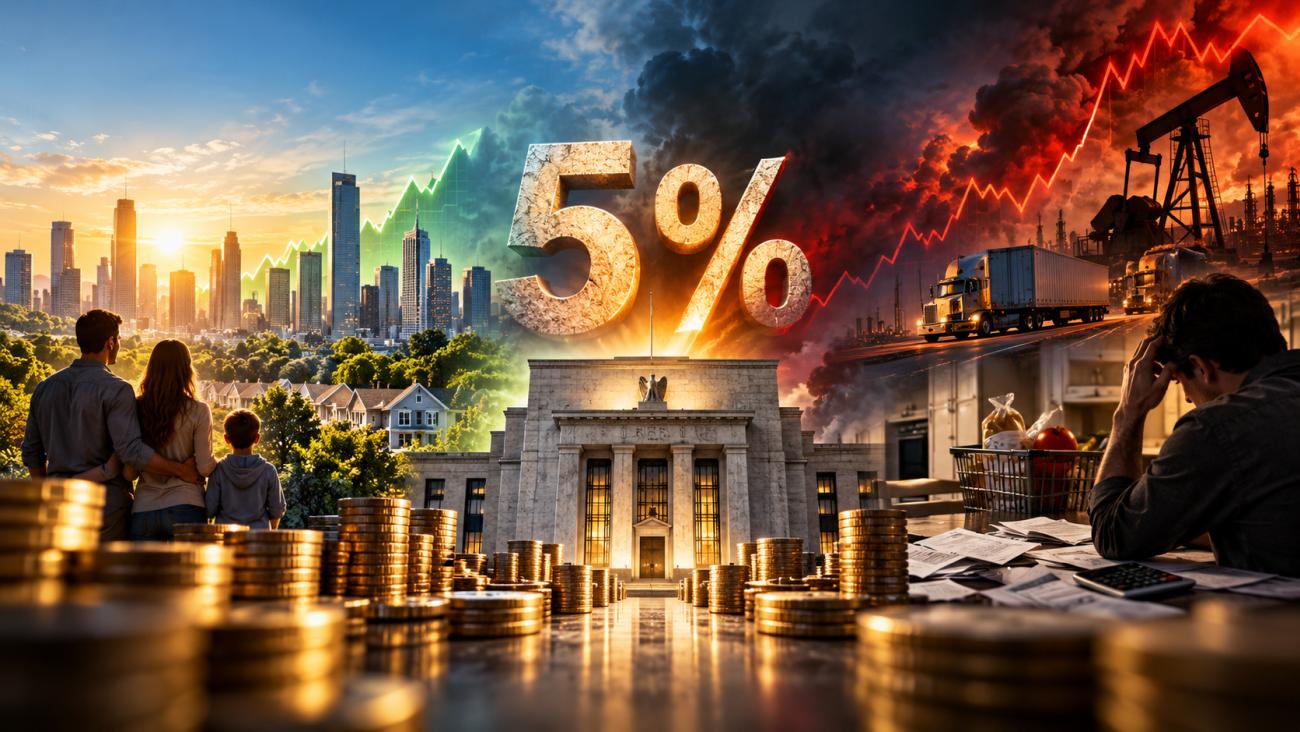
The 10-year Treasury yield has pushed back above 5%, and the long end of the bond market is now trading at levels most investors under 40 have never seen. On Thursday the 10-year touched 5.18% and the 30-year reached 5.47%, the highest readings since 2007 and in 22 years respectively.
Earlier this week we looked at the argument that rising yields are a sign of a strong economy rather than a debt crisis, and that the Fed’s September hike might even work more like stimulus than a brake. That argument gets one big thing right. But it skips a question that matters more to your portfolio than the yield itself: what kind of growth is the bond market actually pricing?
Two economies can produce exactly the same 5% yield. In one, higher rates are a sign of health. In the other, they quietly act as a tax on almost everyone. Figuring out which one we are in is the whole game right now.
The trigger for this week’s jump was a set of business surveys. S&P Global’s flash readings for September showed the US composite PMI at 58.4, with manufacturing at 57.0. Anything above 50 means activity is expanding, so these numbers describe an economy running hot. Traders read that as more inflation ahead and more Fed hikes to fight it, and they sold bonds. When bond prices fall, yields rise.
The effect reached households within a day. Freddie Mac’s weekly survey showed the average 30-year fixed mortgage at 7.03%, up from 6.30% a year earlier. On a typical home loan, that difference adds up to thousands of dollars a year.
There’s a useful rule of thumb for where the 10-year yield “wants” to be. Over long stretches it tends to track how fast the economy grows in dollar terms, what economists call nominal GDP. Nominal growth has two ingredients: real growth (more goods and services actually produced) and inflation (higher prices on the same goods and services).
The logic is intuitive. If the economy’s dollar output is growing around 6% a year, a lender who accepts 3% for ten years is falling behind. So yields drift up toward nominal growth. That’s why some analysts argue that today’s yields are simply catching up with the economy, rather than signalling the fiscal distress we explored in The Fundamental Shift in Global Bond Markets.
The rule is sound. The trap is that it treats both ingredients as if they were the same thing. They aren’t.
Picture two economies that both grow 7% a year in dollar terms.
In the first, output grows 5% and prices rise 2%. Businesses are selling more, hiring more and paying more. A family’s income is rising faster than its costs. When mortgage and loan rates climb, most borrowers can absorb it because their paychecks are growing too. A landlord can lift rents a little because tenants are earning more. The late 1990s looked a lot like this, with real growth often running above 4%.
In the second, output grows only 1.5% and prices rise 5.5%. The dollar figure is identical, so the bond market demands the same yield. But nobody’s standard of living is improving. The extra dollars are mostly going to fuel, transport and whatever costs more this year. Now the higher interest rate lands on households whose pay is not keeping up. It works like a new tax: it drains cash from borrowers without the growth that would normally help them pay it.
Same yield. Very different outcomes for jobs, property and stocks.
The official data lean uncomfortably toward the second picture.
In the second quarter, real GDP grew at an annual rate of just 1.5%, while the PCE price index rose 5.3%. In plain terms, most of the growth in the dollar size of the economy came from higher prices, not from producing more.
The inflation itself is lopsided. Consumer prices were up 3.4% over the year to August, but energy prices rose 16.3% and gasoline 27.4%, while core inflation, which strips out food and energy, was only 2.4%. That pattern matters. Inflation driven by strong demand spreads across everything. Inflation driven by an energy shock concentrates in fuel and then leaks into anything that has to be shipped. Diesel alone has climbed 73% since the Iran conflict began, and diesel is baked into the price of nearly every product on a store shelf.
Then look at pay. Average hourly earnings rose 3.1% over the past year, a touch below headline inflation. The typical worker is standing still or slipping backwards, just as borrowing costs hit two-decade highs. That is the signature of the second economy.
To be fair to the bulls, the picture isn’t one-sided, and that’s what makes this moment genuinely hard to read.
The September surveys were not just about prices. In services, which make up most of the US economy, new orders grew at the fastest pace in over four years and hiring reached its strongest level since June 2022. The August jobs report also surprised on the upside, with employers adding 162,000 jobs against an average of just 31,000 a month over the prior year. If that momentum holds, third-quarter real growth could come in well above the second quarter’s 1.5%, and the first economy would start to look more plausible.
So the honest answer is that the data point both ways. The hard numbers covering the past few months (GDP, wages, core versus headline inflation) favour the “tax” story. The surveys covering right now favour the “boom” story.
There’s one reason to treat the manufacturing boom with a little caution. Most factory PMIs include a measure of supplier delivery times, and it works in a counterintuitive way: when deliveries slow down, the index goes up. The thinking is that in normal times, late deliveries mean suppliers are swamped with orders, which is a sign of strong demand.
In 2026, slower deliveries have another obvious cause. S&P Global reported that supplier delays were the most widespread since July 2022 and input costs rose at the fastest rate since October 2022, with fuel and transport costs widely blamed. Part of the factory “strength” may simply be supply chains struggling with an energy shock. Buyers who expect prices to keep rising also tend to order early, which pulls future demand into today and flatters the current reading.
That caveat has limits. The services survey doesn’t include a delivery-times component, and services delivered the bigger beat. The quirk explains some of the manufacturing surprise, not the whole story.
If higher rates are working as a tax, the first casualties are borrowers who locked in cheap money and now have to refinance.
Apartment owners are the clearest example. Roughly $300 billion of apartment loans come due this year, and landlords are refinancing at about twice the rates they paid five years ago, with some selling at a loss or handing buildings back to lenders. In the first economy, rising tenant incomes would let owners raise rents and cover the higher payments. In the second, tenants can’t absorb it, so the loss moves down the chain to lenders, and from there to the pension funds and insurers that hold commercial property debt.
The same squeeze applies to smaller businesses that borrowed on floating rates, and to households carrying card balances. None of this breaks overnight. It builds quietly until spending starts to give way.
Here’s where the argument gets interesting for anyone positioning for the next year. If the second economy is the right description, today’s high yields may end up causing their own reversal.
The chain works like this. Households spend more on fuel and interest and less on everything else. Retailers and service firms see margins shrink and slow their hiring. Weaker hiring cuts spending further. Eventually real growth stalls, inflation cools as demand fades, and nominal growth falls. Since yields follow nominal growth, they come down too.
We have seen this before. In the first half of 2008, oil soared and long yields rose alongside it. Crude peaked at a record $147 a barrel on July 11, 2008, then collapsed below $40 by December as the global economy seized up. Bond yields tumbled with it. Anyone who celebrated lower borrowing costs at the end of 2008 missed the point: yields were falling because the economy was breaking.
That is the uncomfortable contrarian view. Some well-known analysts now expect the 10-year to test 6%. A plausible alternative is that yields are lower a year from now, but for reasons no investor should cheer. This is a probability, not a certainty. If the services boom proves durable and wages start outrunning prices, the first economy wins and yields can stay high without much damage.
You don’t need to predict the outcome to use this framework. A few practical takeaways:
The bond market isn’t just telling us rates are high. It’s asking whether the growth behind them is real. Over the next few months, the answer to that question will matter far more than whether the 10-year prints 5.1% or 5.4%.
This article is for educational purposes only and is not financial advice. Always consider your own circumstances or consult a licensed adviser before making investment decisions.