Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124

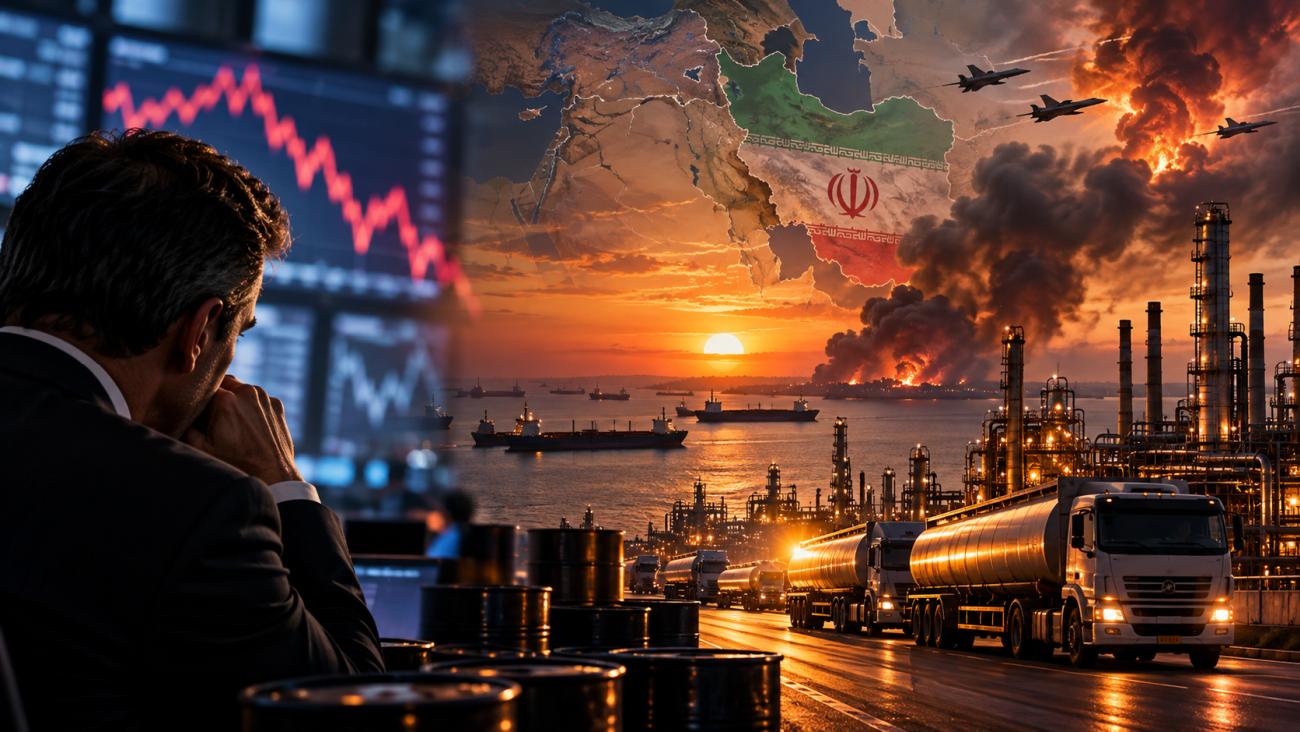
Every so often a major bank publishes a note that tells you more by what it admits than by what it forecasts. In mid-September 2026, JPMorgan’s commodities team, led by Natasha Kaneva, told clients it had abandoned its baseline view on the Iran war and could no longer model how the conflict ends. For a desk whose job is to put numbers on the future, that is a remarkable concession.
The consensus reaction was to shrug and keep watching crude. That misses the story. The most important price in energy right now is not Brent or WTI. It is the margin refiners earn for turning crude into diesel, and it is flashing a warning that most portfolios are not positioned for.
[Also Read: Paper Oil vs Real Oil – The Real Energy Shock]
This analysis draws on a recent PBD Podcast episode from Valuetainment, where the panel debated $10 diesel, recession risk and the politics of the war, and cross-checks their claims against the data.
When the war began on 28 February, JPMorgan built its outlook around a set of economic pain thresholds it assumed Washington would never tolerate. According to Rigzone’s account of the note, those thresholds included $100 oil, gasoline near $5 a gallon, headline inflation at 4% and a 10-year Treasury yield starting with a five. The bank expected those constraints to force a deal to reopen the Strait of Hormuz by June.
An interim deal did arrive in June, then collapsed back into fighting. Six months in, most of the red lines have been breached, the 10-year yield has pushed through 5%, and the path to an exit looks murkier than it did at the start.
The lesson for investors is not that JPMorgan got it wrong. It is that any strategy premised on “they won’t let it get that bad” has already been tested and failed. Political pain thresholds are softer than models assume.
The bank’s valuation work is where it gets interesting. JPMorgan puts fair value for Brent near $90, while the benchmark was trading around $105 when the note went out, after briefly touching $110. Using the bank’s rule of thumb of roughly $4 a barrel for every million barrels a day of lost supply, that gap implies the market is pricing in about 4 million barrels a day of additional disruption on top of the roughly 10 million already offline.
At the same time, the bank noted that global crude inventories have held up better than it originally expected and still offer a meaningful cushion.
Put those together and the picture is clear. A large slice of the crude price is a risk premium: money paid for what might happen, not for barrels that are actually missing. Brent has since swung between the mid-90s and just over $100, which is exactly how a fear-driven price behaves. It gaps on headlines in both directions.
The panel’s sharpest point was that the squeeze has migrated from crude to refined products, and the data backs them up.
By August, DTN’s analysis showed US retail diesel up more than 40% since the war started, while crude was only about 10% higher. The US diesel crack spread, the margin between a barrel of ultra-low sulphur diesel and a barrel of crude, then broke $100 for the first time on record and topped $106 on 1 September, according to Transport Topics. Panel members quoted figures even higher and pegged the pre-war level in the mid-twenties.
The most striking comparison comes from TOPONE Markets. At the previous diesel price record in June 2022, WTI traded somewhere between $110 and $119 with a diesel crack of roughly $64 to $73. In early September 2026, WTI sat near $91.50, yet retail diesel was higher, because the refining margin had widened by about $40 a barrel.
That is the whole story in one data point. Crude is cheaper than in 2022. The fuel the economy actually runs on is more expensive. The constraint is conversion capacity: years of US refinery closures, Russian export restrictions and Ukrainian strikes on Russian refineries, damage to Gulf facilities, and a choked Strait of Hormuz.
This is where the contrarian opportunity, and the trap, sits.
A credible ceasefire headline could knock the fear premium out of crude in days. Refining capacity does not come back on a headline. Damaged plants take months to repair, lost Russian product does not return because of a deal in the Gulf, and closed American refineries are not reopening at all.
That creates an asymmetry most investors are not pricing. Crude carries downside risk if peace breaks out. Diesel carries persistence risk even if it does. US distillate inventories stood at about 107.9 million barrels in mid-September, roughly 13% below the five-year average, heading into the season when heating and harvest demand peak.
Diesel is an input cost for almost everything physical, which is why a diesel shock behaves differently from a gasoline shock. Energy researchers writing in The Conversation cite a congressional Joint Economic Committee estimate that diesel costs added more than $1.4 billion to the cost of planting major US crops this year, a 63% jump on 2025.
Trucking is the transmission belt. James Investment’s analysis notes that about 95% of US carriers run ten trucks or fewer. Small operators cannot absorb record fuel bills for long, and when they fail, hauling capacity shrinks and freight rates rise even after fuel eases.
The panel added hospitality to the list, arguing that independent restaurants without franchise support are already cutting staff. That is anecdotal, but it fits the pattern: discretionary spending is the first line item households cut when fuel and food both rise.
For equity investors, that points to small-cap transport, discretionary consumer names and heavily indebted businesses that have survived on cheap refinancing. With 10-year yields above 5%, refinancing is no longer cheap.
One guest suggested diesel could reach $10 a gallon by December. Treat that as a tail scenario, not a base case. AAA data cited in Valuetainment’s write-up put the national average at a record of roughly $6.45 on 18 September, with California near $8.40. A national $10 print would require another 50% or so from here, which likely means further escalation or a major new supply loss.
Still, the direction matters more than the headline number. Another guest argued that $8 diesel in high-tax states is the tipping point for layoffs, and California is already within touching distance. Investors do not need $10 diesel to get a recession. They need diesel to stay high long enough to erode margins across freight, food and small business.
Record refining margins look like a gift to refiners, and in the short term they are. But political pressure is building. Moneywise reports that Republican lawmakers, including Senator Chuck Grassley, are pushing the White House to ban diesel exports to protect farmers and truckers.
An export ban would likely pull domestic diesel prices down while squeezing refiners that have been selling into tight global markets at premium prices. Windfall tax talk, which surfaced during the 2022 margin spike, could return as well. Refiners are not a one-way bet.
Then there is the calendar. President Trump said on 9 September that oil prices would tumble after the November midterms. Whether that proves right depends on events no one controls, but it does mean policy announcements around the election could move energy prices sharply in either direction.
The oil shocks of the 1970s are the obvious reference points. The 1973 to 1974 Arab embargo nearly quadrupled crude within months. The 1978 to 1979 shock, triggered by the Iranian Revolution, removed about 4.8 million barrels a day of Iranian output and brought rationing back to California.
The takeaway for today is not that prices must go parabolic. It is that supply shocks layered on top of existing inflation pressure tend to stick, and central banks end up tightening into weakness. With headline inflation elevated and the Fed already raising rates, the setup rhymes more than it should.
None of this is personal financial advice, and every portfolio is different. But a few principles follow from the data.
Stop anchoring on crude. If you are using Brent as your proxy for energy inflation, you are watching the wrong gauge. The diesel crack spread and weekly distillate inventory data are better early warnings.
Separate the fear premium from the physical shortage. Crude-heavy positions carry headline risk on any ceasefire news. Refined product tightness is stickier.
Respect policy risk on refiners. Record margins invite intervention, whether an export ban, a windfall tax or both.
Stress-test for a diesel-led slowdown. Transport, discretionary consumer and highly leveraged small caps are most exposed. Duration is exposed too, with the 10-year above 5%.
Keep optionality. When the best-resourced commodity desk on Wall Street says it cannot model the endgame, overconfidence in any single scenario is the real risk.
The crowd is still asking where oil goes next. The better question is why a market with enough crude cannot produce enough diesel, and what that does to an economy that runs on trucks, tractors and freight.
Crude is priced for fear. Diesel is priced for fact. If the war ends tomorrow, the first will fall fast and the second will not. That gap, not the headline oil price, is where the real risk and opportunity sit for the rest of 2026.