Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124

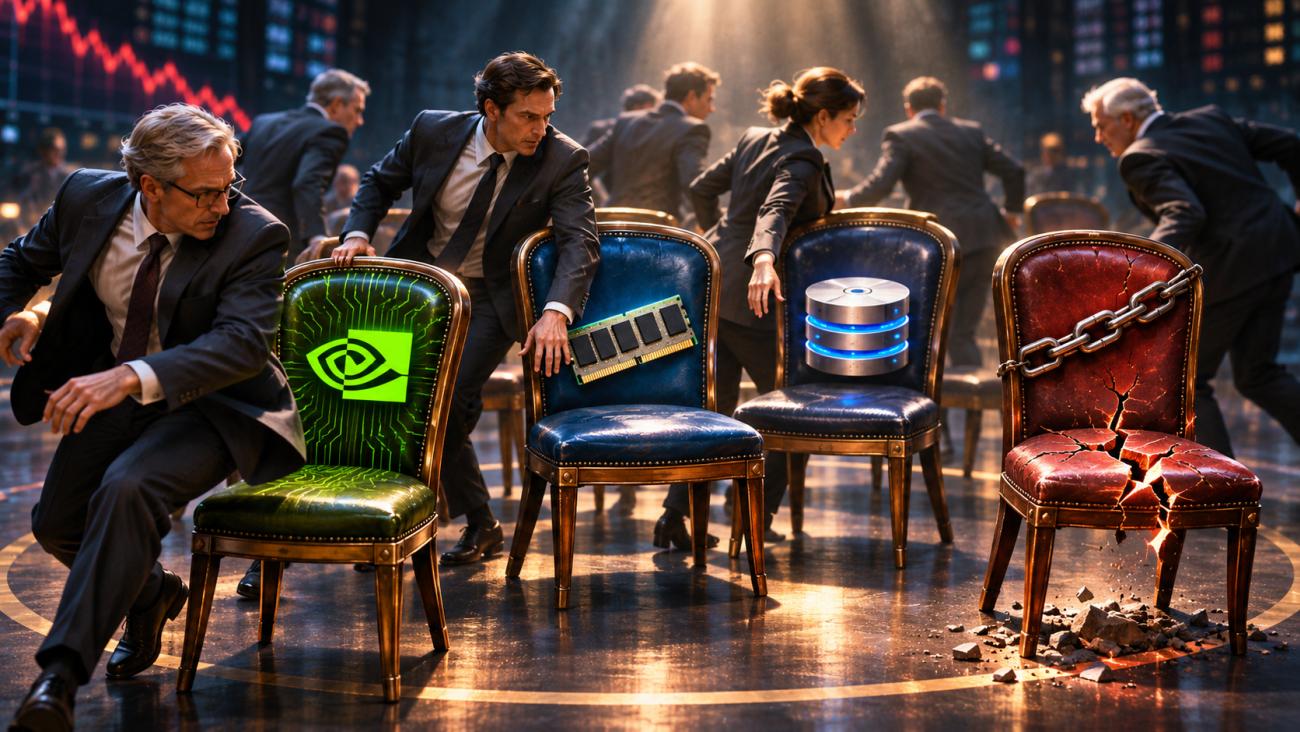
Hedge funds didn't abandon chips in the 2026 selloff. They rotated into memory and storage. The real dot-com echo sits with AI's debt-funded buyers, not Nvidia's valuation.
Every big selloff gets a story, and the chip rout of 2026 already has one. The semiconductor trade, the story goes, is replaying the dot-com bust: the hottest stocks on the planet are cracking, the famous hedge funds sold first, and everyone else is now heading for the exits before the floor gives way.
It is a tidy narrative. It is also becoming the consensus, and that alone makes it worth testing. When you look at what the big investors actually did, what the leading company actually earns, and where the real stress is building, a different picture emerges. The danger in this market is real, but it is not sitting where the headlines say it is.
The damage is not in dispute. The iShares Semiconductor ETF fell roughly 40% from its June high to its early November low, and Nvidia lost its founder and chief executive in the middle of it all. Fund managers have noticed. Bank of America’s November survey showed the net share of investors overweight technology collapsing from 37% to 12% in a single month, the sharpest one-month cut since June 2006, with a record net 38% saying companies are overinvesting in AI.
Much of the money leaving chips went looking for shelter in consumer staples, a crowded hiding place we examined in our look at why gold and bitcoin finished dead last this year.
When a bubble comparison becomes the default framing on financial television and in fund manager surveys at the same time, contrarians should get curious. Not because the comparison must be wrong, but because markets rarely reward the explanation everyone already holds.
The most repeated piece of evidence is that legendary investors dumped their chip stocks during the third quarter. That is true as far as it goes. It just does not go very far.
Renaissance Technologies did cut its Nvidia position from about 7.09 million shares to 23,170. But in the same quarter it raised its Micron stake 619% to $1.62 billion and lifted its AMD holding 140% to $1.21 billion. Micron became its largest reported position. That is not a fund walking away from semiconductors. That is a fund moving from one part of the chip stack to another.
Stanley Druckenmiller’s Duquesne Family Office tells a similar story. It cut its TSMC position from 589,680 shares to 32,700 and exited AMD and SanDisk, yet raised its Seagate stake by 180% and added Seagate call options. Bridgewater trimmed its Nvidia stake by roughly 30%, according to its filing as reported in the Taiwanese financial press, but Nvidia remained its largest single stock holding while the fund added heavily to Qualcomm, Micron and Applied Materials.
Two caveats matter. A 13F is a snapshot of long positions on September 30, filed weeks later, so it reveals nothing about shorts, hedges or trades since. And Renaissance runs quantitative models that turn over constantly, so no single line in its filing represents a human conviction. Even so, the pattern across these filings is rotation within hardware, especially toward memory and storage, not a wholesale escape from it. “The smart money is out” is a much less accurate summary than “the smart money changed seats.”
The dot-com comparison also struggles with the arithmetic at the center of this boom. Nvidia reported fiscal third-quarter revenue of $115.8 billion, net income of $65.3 billion and guidance for $130 billion of revenue next quarter. With a market value of roughly $3.8 trillion on results day, annualizing that single quarter of profit puts the stock at around 14 times earnings by my arithmetic. Cisco, the networking darling at the heart of the 2000 bubble, traded at more than 200 times earnings at its peak.
That difference shapes what recovery looks like. Cisco survived the bust as a business, yet its shares only regained their March 2000 high in December 2025, and even then the company’s market value was still roughly $250 billion below its dot-com peak. A company priced at 200 times profit needs decades for earnings to grow into the price. A company priced in the teens does not, as long as the profit is real and durable.
That condition is the whole question. And it is where the analysis needs to shift from the stock chart to the balance sheets.
If there is a genuine echo of 2000, it is not in price multiples. It is in how the buying is being paid for.
The International Monetary Fund now estimates circular financing among AI companies at just over $1 trillion, roughly two-thirds of it borrowed, and Managing Director Kristalina Georgieva warned this month that the global economy is leaning on AI as if standing on a single leg. Circular financing means money that flows from a supplier or investor into a customer comes straight back as orders, which flatters demand while the cycle lasts.
Nvidia sits in the middle of some of these arrangements. After talks over a guarantee reportedly worth $250 billion, it signed an Ohio data center deal that caps its exposure at $105 billion, backs the value of the buildings rather than OpenAI’s rent, and requires OpenAI to reimburse anything Nvidia pays out. That reimbursement promise is only as good as OpenAI’s own finances. Nvidia’s forward commitments to suppliers also jumped to $390 billion from $279 billion in a single quarter, driven mainly by expensive memory bought under long-term contracts.
The more fragile seats belong to the borrowers who rent out the hardware. Oracle sent a force majeure notice to the developer of a delayed New Mexico data center project, and its bonds due in 2055 traded at 77 cents on the dollar. CoreWeave grew from three data centers to 51 in four years and reportedly carries around $50 billion in outstanding obligations, financed largely with bonds.
This is the part of the market where a 2000 style unwind would actually bite. A profitable seller with modest valuation can absorb a slowdown. A leveraged buyer whose revenue depends on renting out chips at today’s prices cannot.
Jensen Huang’s resignation on November 12 was treated as pure bad news, and the uncertainty is real. But consider who replaced him. Interim chief executive Colette Kress, Nvidia’s finance chief since 2013, reportedly pushed back on the original $250 billion OpenAI backstop while Huang championed it. The guarantee Nvidia eventually signed was smaller, and by that report’s arithmetic still equal to about 1.9 times the company’s cash and marketable securities at the end of July.
If the biggest risk to Nvidia is the financing it extends to customers rather than the chips it sells, then a more conservative hand on the balance sheet is arguably a reduction in tail risk. Markets tend to price founder departures as a loss of vision. In this specific case, it may also be a loss of appetite for exactly the type of deal that worries the bears most.
None of this means the bottom is in. In fact, the positioning data argues the opposite. Even after November’s record cut, fund managers were still net overweight technology. Bank of America’s own strategists noted that historically the best entry points came after tech positioning flipped to underweight, and that the survey still showed too little fear to signal a buy. Long semiconductors also remained the single most crowded trade in the survey.
So the contrarian position here is not “buy the dip.” It is that the crowd may be fleeing the wrong seats. Selling the profitable, reasonably valued supplier while ignoring the debt-funded buyers is the reverse of what the 2000 experience actually teaches.
Hyperscaler spending guidance from late January. Amazon, Alphabet, Meta, Microsoft and SpaceX are on track for $803 billion to $828 billion of capital spending this year, and Alphabet and Amazon have both signaled meaningfully higher outlays in 2027. Any retreat from those plans would be the clearest sign that demand, not just sentiment, is turning.
Nvidia’s supply commitments in late February. Revenue will get the headlines. The more useful number is whether that $390 billion of forward purchasing keeps climbing faster than sales.
Credit spreads on the borrowers. Bond prices and default swap costs for the most leveraged AI infrastructure names tend to move before their shares do. If Oracle and the neocloud lenders stabilize, the systemic risk case weakens. If they keep widening, the equity selloff has further to run regardless of how strong Nvidia’s quarter looks.
The bubble comparison is not baseless. There is too much borrowed money moving in circles, and some of the companies holding that debt look uncomfortably like the casualties of 2001. But history did not punish every company at the center of the internet buildout equally. It punished the ones that had to keep borrowing to stay alive.
That is where this market’s real risk lives, and it is also why the loudest version of the 2000 rerun story may be pointing investors at the wrong exits. The famous funds did not abandon semiconductors. They moved to seats they judged safer. The useful question for every investor is not whether to own chips at all, but which seat in the financing chain each holding occupies, and who is paying for the hardware when the music slows.