Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124

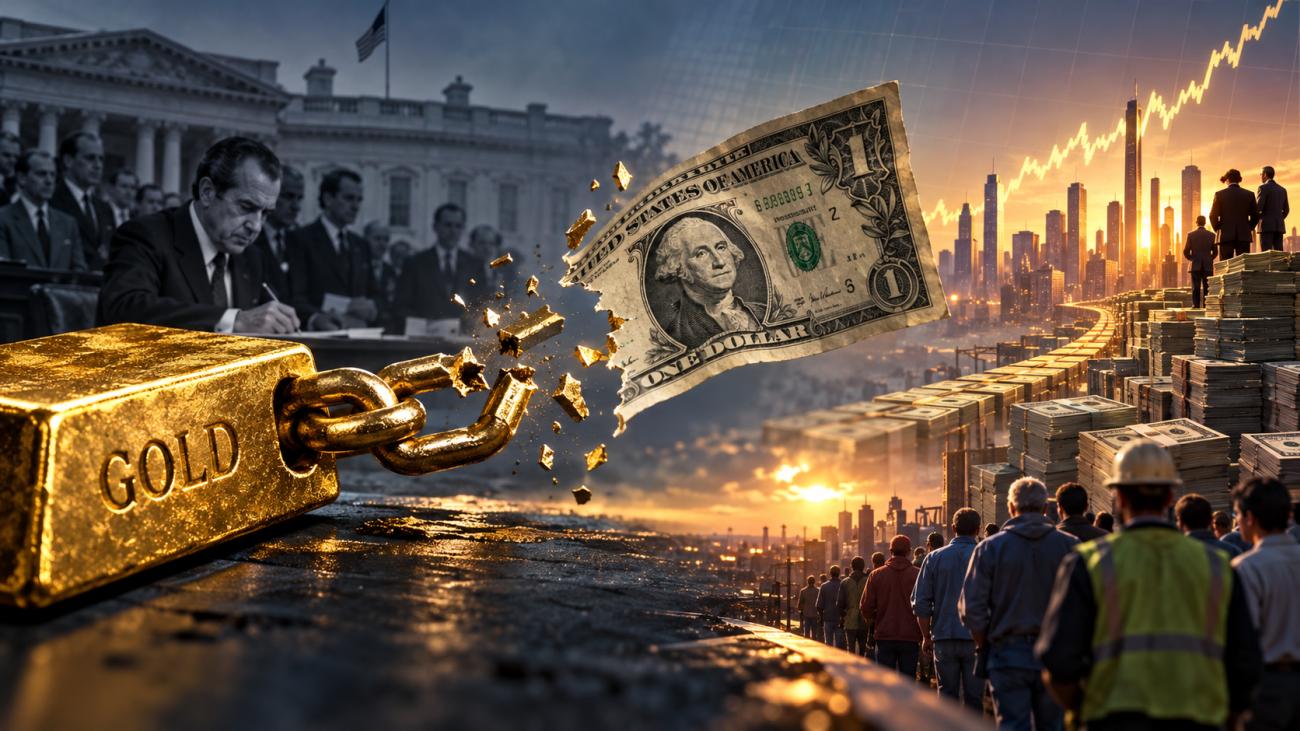
When the dollar was cut loose from gold in August 1971, the rules of money changed, and the rules of money decide who gets rich and who falls behind.
There is a popular corner of the internet that blames 1971 for almost everything: wages, house prices, obesity, divorce, even the number of lawyers. It is easy to laugh at. Some of those charts are coincidences, and some lean on clumsy statistics.
But throwing out the whole argument because the meme overreaches would be a mistake. Strip away the noise and a serious case remains. Since the last link between the dollar and gold was broken, money has steadily lost value, new money has flowed first to those who already own assets, debt has become the engine of the economy, and the financial system has become more crisis prone. None of that is a conspiracy theory. It is in the data published by central banks and statistical agencies themselves.
On a Sunday evening in August 1971, the United States stopped letting foreign governments swap their dollars for gold at $35 an ounce. Ordinary Americans had already lost that right decades earlier. What ended in 1971 was the last hard limit on how many dollars the world’s reserve currency could create.
The Federal Reserve’s own history of the episode is candid about why it happened. Under the post-war Bretton Woods arrangement, other currencies were pegged to the dollar and the dollar was pegged to gold. Through the 1960s, spending on war and foreign aid pushed more and more dollars abroad while the gold stock barely grew. Eventually foreign-held dollars outnumbered the gold available to redeem them, and a run on Fort Knox became a real possibility. Rather than tighten, Washington closed the window. Fixed exchange rates limped on for a short while and then gave way to floating currencies by early 1973.
Notice what that means. The gold link did not snap because it failed to discipline governments. It snapped because governments no longer wanted to be disciplined. From that point on, the only constraint on money creation was the judgement of central bankers and the patience of bond markets.
A 1971 dollar now buys about 12 cents’ worth of goods. That is not a fringe estimate. It falls straight out of the official consumer price index, which stood at roughly 40 in 1971 and reached 336.9 in September 2026. Prices have risen more than eightfold in a single working lifetime.
Measured against gold, the picture is starker. An ounce cost $35 when the window closed. In mid-October 2026 it traded around $4,150, after touching records above $5,000 earlier in the year. In gold terms, the dollar has lost roughly 99 percent of its value.
Defenders of the system say a steady 2 to 3 percent inflation rate is healthy, and in any single year it barely registers. That is precisely the point. Debasement under a fiat standard rarely arrives as a shock. It arrives as a slow leak that compounds quietly over decades, and the people who suffer most are those who hold their wealth in cash, savings accounts and fixed pensions. Under a gold anchor, saving was a sensible strategy for ordinary families. Under a floating dollar, sitting in cash for the long haul is a reliable way to lose ground.
New money never reaches everyone at the same time, and the order in which it arrives decides who wins. Economists call this the Cantillon effect, after an 18th-century banker who noticed that whoever spends freshly created money first gets to buy at yesterday’s prices. By the time it trickles down to wage earners, prices have already moved.
In a fiat system, the first recipients are banks, bond markets and asset holders. Central banks create money by buying financial assets, which lifts the prices of those assets. This is not a theory dreamt up by gold enthusiasts. After its own quantitative easing programme, the Bank of England concluded that its purchases had pushed up equity prices by at least as much as government bond prices, and acknowledged that the policy had unavoidable distributional consequences. Put simply, if you already owned shares and property, the money printer worked for you. If you only owned your labour, it did not.
[Also Read: If Every Country Is In Debt Who Do They Owe the Money To?]
The long-run result shows up in how the economy’s output is divided. In 1971, workers in the US nonfarm business sector took home about 63 percent of what they produced in wages and benefits. By the second quarter of 2026, that share had fallen to 52.8 percent, the lowest level ever recorded. The slide was gradual at first and sharpened after 2000, in exactly the era when interest rates were pushed toward zero and central bank balance sheets exploded. A larger slice of the pie now goes to capital, and capital is owned by people who were already wealthy.
When money can be created without limit, debt stops being a burden to be paid down and becomes a permanent feature of the economy. That shift is visible everywhere you look after 1971.
Start with government. In 1971 the US federal debt was less than half a trillion dollars. In August 2026 it passed $40 trillion, only five months after crossing $39 trillion. Borrowing a trillion dollars in five months would have been unthinkable when every dollar was, at least in theory, a claim on a fixed pile of gold.
Then look at households and the financial industry that serves them. Harvard economists Robin Greenwood and David Scharfstein found that the US financial sector grew from 4.9 percent of GDP in 1980 to 7.9 percent in 2007. Much of that growth came from two sources: asset management fees that rose with soaring share prices, and fees earned from a huge expansion of household borrowing, mostly mortgages. In their paper, household credit roughly doubled as a share of GDP over the same period.
This is the part of the 1971 story that matters most for ordinary people. Houses got bigger, but not by nearly enough to explain what happened to their price. They became financial assets, priced by how much credit could be extended against them. A young family today is not just buying a home. It is bidding against cheap money, and the winner is whoever can borrow the most.
The floating-money era has also been far more prone to financial crises. This is one of the strongest pieces of evidence in the whole debate, because it comes from mainstream economic historians rather than gold advocates.
Michael Bordo, Barry Eichengreen and their co-authors built a database spanning 120 years of financial history. Their finding was blunt: crisis frequency since 1973 has been double that of the Bretton Woods and classical gold standard periods, rivalled only by the chaos of the 1920s and 1930s. Under Bretton Woods, with capital controls and tightly regulated banks, the same researchers found virtually no banking crises for the better part of four decades.
Their explanation is worth noting. They point to the combination of free-flowing global capital and an expanding financial safety net. Translated into plain language, banks learned that if they took big enough risks, a central bank with an unlimited printing press would eventually catch them. Gains stayed private. Losses were socialised through bailouts, rate cuts and fresh money creation, which pushed asset prices up again and set the stage for the next boom. A hard monetary anchor made that cycle far harder to sustain.
Shrinkflation is the one part of this story shoppers notice with their own eyes. The chip bag has more air, the paper towel roll has fewer sheets, the chocolate bar is a little thinner, and the price stays the same.
It is tempting to blame shrinkflation for the cost-of-living squeeze, but the official data says it is a small slice of the problem. The US Bureau of Labor Statistics found that product downsizing added only about 0.01 percent a year to overall inflation, even though it hit categories like snacks, baby food and household paper products noticeably harder.
That finding actually strengthens the larger argument. Shrinkflation is not the disease. It is the camouflage. Companies shrink packages because shoppers react more sharply to a higher sticker price than to a smaller product, and they need a way to pass on rising costs without triggering that reaction. The real story is the general rise in prices underneath, the slow erosion of what a unit of currency can buy. A shrinking chocolate bar is simply the place where an abstract monetary process becomes something you can hold in your hand.
A serious argument has to face its best objections, and the defenders of floating money have real ones.
First, Bretton Woods was not killed by a single bad decision. The Federal Reserve’s own account describes years of swap lines, gold pools and emergency fixes that were only postponing the inevitable, because a single country cannot supply the world’s reserve currency and keep it fully backed at the same time. Something had to give.
Second, gold has its own ugly record. The interwar gold-exchange standard helped spread the Great Depression from country to country, and Bordo and Eichengreen note that nations only escaped the worst of the slump once they cut their link to gold and reflated. Their research also found that while crises have become more frequent since 1973, there is little evidence they have become longer or deeper.
Third, correlation is not causation. The early 1970s also brought the first oil shock, a flood of baby boomers and women into the workforce, and the start of a long wave of globalisation and automation. Many economists attribute the falling labour share to those forces, or partly to how it is measured, rather than to the monetary regime. And most economists still regard a return to a gold standard as impractical and potentially dangerous.
These are fair points. But notice that none of them disputes the core of the argument made here. Nobody seriously denies that the dollar has lost most of its purchasing power, that central bank money creation lifts asset prices first, that debt has exploded, or that crises have become more frequent. The disagreement is over whether those costs were a price worth paying for flexibility. That is a legitimate debate. Pretending the costs do not exist is not.
You do not need to believe gold will return to make use of this history. You only need to accept that the rules set in 1971 are still the rules today, and that they reward owners of real assets and punish holders of idle currency.
A few principles follow from that.
The meme asks what happened in 1971. The more useful question for an investor is simpler: in a world where money has no anchor, which side of the money printer are you standing on?